New - 1 Hour Ago


$300,000
Active
3
Beds
3
Baths
2009
Sqft
0.23
Acres
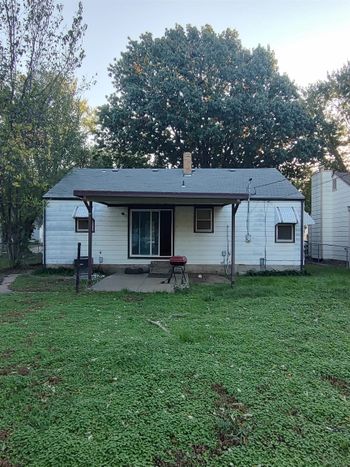
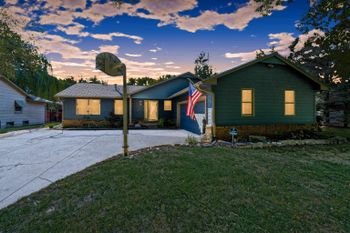
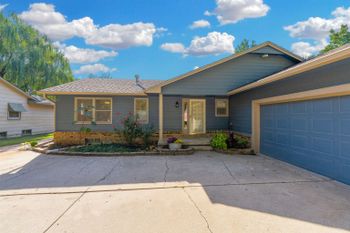
3227 N Westwind Bay Ct, Wichita, KS 67205-2525
MLS#: SCK681356


Imagine two Wichita homebuyers who expected their mortgage applications to move smoothly toward closing.
The first receives a request for another bank statement. The second learns that the home's lower-than-expected appraised value does not support the proposed financing terms, so the lender cannot approve the mortgage as structured. Both hear that their mortgage is on hold, but they face very different problems.
One may need to provide a missing record. The other may have to review the appraisal, reconsider the financing or negotiate with the seller.
A third buyer might discover that the income used for mortgage qualification is lower than the amount they actually earn.
When a mortgage application is delayed or denied, the first step is to identify the exact obstacle. Changing jobs, paying off debts, moving money or applying with another lender may help in some circumstances. In others, those actions can complicate the application without addressing the real problem.
Here's how to find out what is happening and choose a next step that fits your situation. If you're already under contract, check the financing and closing dates in your signed agreement while you clarify the loan's status.
Before trying to fix anything, establish whether the lender has actually made a decision.
Mortgage underwriting is the process of evaluating your income, debts, credit, available funds and proposed property against the applicable loan requirements. A request for more information means something different from an outright denial. A conditional approval also means there are requirements to satisfy before the loan can proceed to closing.
Even a preapproval letter is not a guarantee of final financing. The Consumer Financial Protection Bureau explains that lenders use prequalification and preapproval differently, sometimes reviewing substantially different amounts of financial information.
Start with a written request to your lender:
Is the application pending, incomplete, conditionally approved or denied?
What exact document, calculation or requirement is preventing progress?
Does the issue come from the loan program or from this lender's own requirements?
Who needs to provide or review the next item?
When can I expect a response, and could resolving the issue involve additional costs?
A missing pay stub, for example, may be a straightforward documentation problem. But if the lender already reviewed your pay information and determined that your qualifying income is insufficient, another copy of the same pay stub will not necessarily change the decision.
Federal Regulation B generally requires lenders to notify applicants of a credit decision within 30 days after receiving a completed application. An application is considered complete when the creditor has the information it normally uses to make that decision.
That rule does not guarantee a mortgage closing within 30 days.
An incomplete application follows different procedures. If the lender issues a formal written notice of incompleteness, it must identify the missing information and give a reasonable deadline for responding. Missing that deadline can end consideration of the application. A late response may require a new application.
Not every ordinary request for an updated document is a formal incompleteness notice.
When an application is denied, the adverse-action notice must provide the specific principal reasons or explain how to request them within 60 days of the lender's notification. If you request those reasons on time, the lender generally has another 30 days to provide them.
These distinctions are explained in the CFPB's Regulation B notification rules. A rejected preapproval request can also trigger adverse-action notice requirements in certain circumstances, although an informal prequalification conversation does not necessarily qualify as an application.
You may already have received a Loan Estimate—a standardized lender form showing proposed loan terms and estimated costs—without receiving a credit decision. For most covered mortgages, providing six details—your name, income, Social Security number, property address, estimated property value and requested loan amount—generally triggers that disclosure within three business days.
A Loan Estimate, even one showing a locked interest rate, is not final approval. The CFPB's Loan Estimate guidance explains the distinction. Provide sensitive application information only through the lender's secure channels.
Your household income and your qualifying mortgage income are not necessarily the same amount.
Consider someone who works a salaried job and recently began earning additional money through a side business. Both income sources help pay household expenses. Yet the lender might accept the wages while excluding the newer business income or requesting more history before considering it.
That distinction can change the size of the mortgage for which the buyer qualifies.
Find out which income sources were accepted, which were excluded and whether the problem is missing documentation or a requirement the income does not satisfy.
The CFPB's mortgage paperwork guide recommends keeping income and financial records current. Depending on the situation, the lender may need pay stubs, bank statements, tax returns or records related to self-employment, commissions or seasonal work.
A recent job change deserves careful attention, too.
There is no universal requirement that every mortgage applicant must have worked for the same employer continuously for two years. Fannie Mae sets standards for many conventional mortgages, which are not government-insured or government-guaranteed loans. Under Fannie Mae's employment-income standards, lenders evaluate whether employment reflects a reliable pattern over the recent two years. Shorter histories can be acceptable in certain circumstances, and consistent earnings through different employers may qualify.
Multiple jobs and self-employment have additional income-specific rules. FHA, VA and USDA loans follow different government-backed programs; a portfolio mortgage is kept by the lender rather than sold. Fannie Mae's standards do not automatically determine eligibility for those other loans.
The important question is not simply whether you've earned the money. It's whether the applicable loan requirements allow the lender to use that income and whether you can document it.
Before taking another job or starting new work to improve your application, find out what records and income history would actually be required.
Even when your income is documented, the amount needed for your existing debts and proposed housing payment can affect approval.
Lenders use a debt-to-income ratio, or DTI, to compare required monthly debt payments with gross monthly income. For mortgage qualification, the income must also meet the lender's verification and eligibility requirements.
The CFPB explains how DTI works. Different loan products and lenders have different limits, so the often-mentioned 43% figure is not a universal cutoff.
If DTI is the obstacle, request the amounts used in the calculation. Check the existing debts, qualifying income and proposed housing costs, including applicable property taxes, insurance and mortgage insurance.
Two Wichita homes with similar asking prices may produce different monthly ownership costs.
One property might have special assessments, commonly called specials, that another property does not. These charges can fund improvements such as streets, water lines or sewer infrastructure. The City of Wichita explains special assessments and how designated properties share improvement costs.
For a home in Sedgwick County, the county's property tax bill guide shows where to find the property's address, tax year and special-assessment summary.
A previous tax bill is a starting point, not a guarantee of future charges. Not every Wichita home has specials, and a Wichita mailing address does not necessarily establish the property's exact taxing jurisdiction.
That is why an estimate based only on purchase price can be misleading. Have the lender verify the relevant property's taxes, assessments and insurance costs rather than relying on broad estimates.
Also check whether each cost is included in the proposed escrow payment or must be paid separately. An escrow account is managed by the lender or loan servicer, which collects money with your mortgage payment and uses it to pay property tax and insurance bills. Either way, the costs remain real ownership expenses.
If the resulting housing cost is higher than expected, a different loan amount or property may be worth considering. But changing the purchase price is not the only possible response, and it will not necessarily resolve a separate income or credit requirement.
The same caution applies to paying off debt. Reducing a monthly obligation might improve DTI while using money needed for closing or required reserves—funds some loans require you to keep after closing. It could also generate new documentation requests.
Have the lender evaluate the effect on the entire application before making the payment.
A lender's comment that your credit is insufficient does not tell you everything you need to know.
Was the decision based on an inaccurate account balance, payment history or another entry in your credit report? Or was the information accurate but outside the requirements for that particular loan?
Those situations call for different responses.
If the lender denied the application based wholly or partly on information in a consumer report, federal law provides additional disclosure rights. The notice identifies the credit reporting company involved and explains your right to obtain a free report from that company within 60 days after receiving the notice.
When the lender used a numerical credit score in taking the adverse action, the applicable disclosures also include that score and key factors affecting it.
Those credit-score factors are not necessarily the lender's specific reasons for denying the mortgage. The credit bureau supplies information; it does not make the lending decision.
The CFPB's guidance on credit-related denials explains what to review.
If you find inaccurate information, dispute it with both the reporting company and the business that furnished the information. A correction does not guarantee a particular score increase, mortgage approval or closing date.
If the negative information is accurate, ask which lender or loan-program requirement it affects. You need to know what would have to change before another application could succeed.
There is no single credit-score threshold that determines eligibility for every Wichita homebuyer. Loan programs, underwriting circumstances and lender requirements differ.
Avoid opening unrelated credit accounts or financing another major purchase while the application is being reviewed without first considering the effect. New borrowing can change your credit profile and required monthly payments. The CFPB explains how mortgage credit checks differ from other credit activity.
A buyer who has saved the planned down payment can still discover that the lender needs more money or documentation.
The down payment and closing costs are separate expenses. Your cash to close reflects the down payment, closing expenses and adjustments for deposits, agreed seller credits and other applicable amounts.
Your Loan Estimate separates these figures and identifies estimated taxes, insurance and assessments. Certain costs remain payable even when they are not part of escrow.
Compare the estimate with the funds you actually have available. Then determine whether the lender is questioning the amount, the source or the documentation.
For example, someone who recently moved savings between bank accounts may have enough money but still need to document the transfer. A buyer receiving funds from another person may have to show that the contribution satisfies the loan's requirements.
Adding money without addressing those questions may not resolve the issue.
Ask for the exact cash-to-close amount, funds already credited, any required reserves and documentation needed to verify the remaining money.
Before making a large transfer, depositing additional funds or accepting financial assistance, confirm which sources and records the lender can accept.
A mortgage application can reach the property review with the buyer's finances in acceptable shape and still encounter an obstacle.
The issue may be the appraised value, a lender-required repair or another property eligibility condition. These are not interchangeable.
Imagine a buyer who agrees to purchase a Wichita home, but the completed appraisal supports a lower value than the contract price. The lender may not be willing to finance the original amount under the proposed terms.
That could lead to a discussion about the loan amount, additional funds, a possible price negotiation or the appraisal itself.
A lender-required repair creates a different problem. It may require specific work, additional evidence or another inspection before the lender will proceed.
Find out exactly what condition remains unresolved, who must confirm that it has been satisfied and whether the process involves added costs.
Remember that a lender's appraisal serves a valuation and financing purpose. It does not guarantee the home's overall physical condition or replace a broader home inspection.
An appraisal is not necessarily beyond review.
For Fannie Mae loans requiring an appraisal report, lenders must maintain a borrower-initiated reconsideration-of-value process. The process can address concerns that the value is unsupported, appraisal practices are deficient or prohibited discrimination may have affected the report.
A buyer who finds factual errors or has relevant supporting information can submit the concern through the lender's established process.
Under Fannie Mae's appraisal-quality requirements, only one borrower-initiated reconsideration is permitted per appraisal. The lender must provide information about the process when supplying the report.
This does not guarantee a higher appraisal or mortgage approval. Ask what process applies to your actual loan rather than assuming every program follows identical rules.
You may also be entitled to a copy of the appraisal or other written valuation, even if the mortgage is denied.
For an application involving credit secured by a first lien on a dwelling—meaning a mortgage with priority over other mortgage liens on the home—Regulation B generally requires copies of valuations developed for the application. They must ordinarily be provided promptly upon completion or at least three business days before closing, whichever is earlier.
A permitted waiver can change delivery timing but does not eliminate the right to copies. If the transaction will not close after such a waiver, the lender generally must provide the copies within 30 days after determining that closing will not occur. The rule does not require the lender to produce an appraisal that was never developed.
Getting another lender's assessment may be worthwhile, particularly if the original problem involves a requirement specific to that lender.
Suppose one lender has a restriction that is stricter than the requirements of the loan program you're considering. A different lender may assess the application under its own standards.
But if the application is missing required income documentation or the property fails a program eligibility requirement, changing lenders does not automatically fix the problem.
You can contact another licensed lender without first obtaining a formal written improvement plan. Explain the original obstacle and ask whether its underwriting process offers a different approach.
Keep in mind that the second lender may need to verify income, credit, assets and the property again. It may also have different costs.
Compare offers using comparable loan amounts, terms and products. Review current Loan Estimates, paying attention to the total monthly housing payment, cash to close and upfront lender charges rather than looking only at the interest rate.
Another quote is an opportunity to compare options, not a guarantee that the loan will close.
If you need independent help understanding credit, budgeting or homebuying requirements, a housing counselor approved by the U.S. Department of Housing and Urban Development (HUD) may be useful. Not every participating agency provides every service, so confirm what is available before scheduling.
Homebuying counseling may involve a reasonable disclosed fee, but participating agencies must waive the fee when the client cannot afford it. Counseling does not guarantee mortgage approval.
A mortgage delay becomes more complicated when the purchase agreement has a financing deadline or scheduled closing date.
You may still be gathering employment records while the lender's rate lock approaches expiration. Or you may be comparing a second lender's proposed terms without knowing whether that lender can complete its review before closing.
These are separate problems that need to be considered together.
First, verify that your original lender has received the records and any required confirmation of your intent to proceed. The CFPB explains what intent to proceed means.
Then confirm the expected underwriting schedule and any applicable rate-lock expiration or extension cost.
Next, review the financing and closing dates in your signed purchase agreement. A lender's estimated completion date, or a request for more documentation, does not automatically change those contractual deadlines.
Your real estate agent can help identify relevant dates and property-related questions. A Kansas attorney should explain what the agreement requires, whether a notice or amendment may be needed, and the legal effect of a missed deadline.
A mortgage denial does not automatically cancel the purchase contract, extend the closing date or guarantee a return of earnest money. Those consequences depend on the actual agreement and applicable law.
If the entire homebuying process needs reconsideration, the Wichita first-time homebuyer guide covers budgeting, offers, inspections and closing.
The best next step depends on what the lender has actually found.
A missing document may be resolved by submitting the required record. A disputed credit-report error needs investigation and supporting evidence. Insufficient qualifying income may require another loan amount or product. A property condition may require a repair, valuation review or a different property decision.
Not every problem requires starting over, and not every problem can be resolved by waiting.
Before paying down debt, opening or closing a credit account, moving funds, changing employment or committing to different financing, ask how that action would affect the rest of the application.
A useful written response from the lender should identify the exact issue, the change or document required, who will review it, the expected timing, any added cost and what requirements would remain afterward.
If you're still at the conditional preapproval stage, see the Wichita mortgage preapproval guide for more about preparing the required records. For broader comparisons of financing programs, visit the guide to first-time homebuyer mortgage options.
Urban Cool Homes can help with Wichita-area property questions, home searches and the real estate transaction. If you've already signed an exclusive representation agreement with another brokerage, review and honor its terms before seeking representation elsewhere. Mortgage eligibility and approval remain the lender's responsibility, while legal questions about contract rights or deadlines should go to a Kansas attorney.
A stalled mortgage application can feel like a setback without a clear direction. But a delay caused by one missing record is not the same as a loan that cannot meet an underwriting requirement.
Find out which problem you actually have. Then you can evaluate the documents, costs, timing and financing choices that matter—without making changes that solve the wrong problem.